Lee Swee Eng: The Engineer Who Built KNM Into a Global Name — And the Ruin That Followed
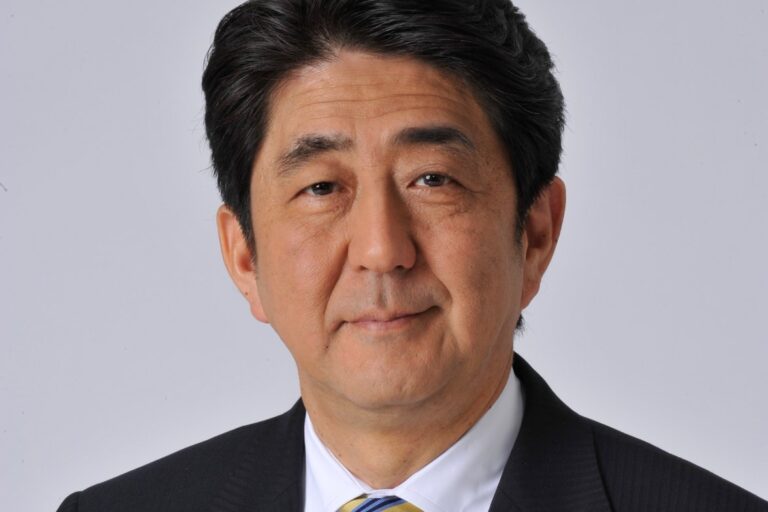
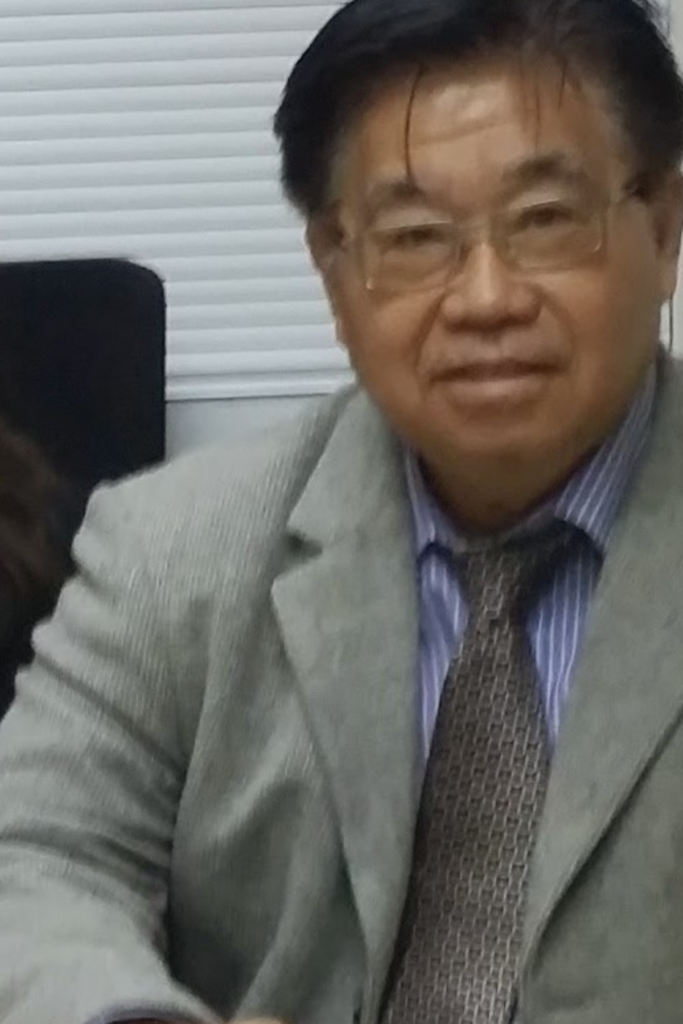
For most of two decades, Lee Swee Eng was one of the more visible self-made industrialists in corporate Malaysia. The engineer turned the small fabrication outfit he founded into KNM Group Berhad, a Bursa Malaysia-listed maker of process equipment for the oil, gas and petrochemical industries with operations across Asia, Europe and the Middle East. By November 2025 the company he built had been struck off the exchange entirely, its business gone and its remaining foreign units left to be sold off to chip away at debts its assets could not fully cover.
Lee himself had left behind a civil insider-trading judgment recorded against him. The arc from that founding to that ending is one of the more instructive rise-and-fall stories in the Malaysian market, and it is worth setting out strictly as the record has it.
An engineer’s beginnings
Lee holds a first-class-honours degree in mechanical engineering from the University of Strathclyde in Glasgow, awarded in 1979. He became a registered professional engineer in 1984 and a Fellow of the Institution of Engineers, Malaysia, in 1993. Before going into business for himself he worked between 1976 and 1990 at Exxon, national oil company Petroliam Nasional Bhd, John Brown E&C and Technip Geoproduction (Malaysia), accumulating the process-plant experience that would define his company.
In 1990 Lee, together with his wife Gan Siew Liat, started KNM as a private process-equipment manufacturer. The business was floated on Bursa Malaysia in 2003, and Lee was appointed group managing director on 14 June that year. KNM grew into a supplier of pressure vessels, heat exchangers and modular process systems to energy and petrochemical clients worldwide.
The peak, and the debt behind it
KNM’s high-water mark came during the pre-crisis commodities boom. By 2007 the group carried a market capitalisation of roughly RM8 billion, and Lee’s shareholding of about 26% put his paper wealth above RM2 billion, earning him a place among Malaysia’s billionaires.
The most consequential move of that era was the 2008 acquisition of Germany’s Borsig, a maker of specialist process and industrial equipment, for about €350 million (roughly RM1.67 billion at the time). The deal transformed KNM from a regional fabricator into a group with European technology and a global client list, and Borsig would become the single largest earnings contributor to KNM, generating around RM100 million a year in pre-tax profit. But the expansion was heavily debt-funded, and the borrowings left a lasting mark: by the 2020 financial year, finance costs of about RM60 million were swallowing some 40% of the group’s operating profit.
A second ambitious bet was a 36-megawatt waste-to-energy plant in Peterborough in the United Kingdom, first flagged around 2010. KNM only secured financing for it in 2017, held back by a stretched balance sheet, and completion slipped repeatedly past its original targets.
The turn
The oil-and-gas downturn of the mid-2010s hit KNM hard. As crude prices collapsed, orders for the process equipment that was KNM’s core business dried up, and the company’s valuation fell with it. By July 2016 Lee’s fortune had shrunk so sharply that The Star reported he had gone “from billionaire to millionaire in less than four months.” He had been named executive chairman and group CEO in September 2010 and relinquished the executive chairmanship in April 2013.
The Thai ethanol venture — a family affair
One of KNM’s most damaging diversifications was into fuel ethanol in Thailand, through Impress Ethanol Company Limited — a plant at Hinsorn, Phanom Sarakham District, Chachoengsao Province, with registered capital of THB942 million. The venture was controlled by the Lee family through a pair of Mauritius holding companies, Asia Bio-fuels Limited (ABL) and Asia Biofuels II Ltd (ABL II), which between them held about 72% of the ethanol operation (roughly 49.85% via ABL II and 22.14% via ABL, alongside a Thai fund’s 23%).
The family sat squarely at the controls. Lee Swee Eng’s daughter, Sara Lee Mei Ching, was an appointed director of both Mauritius vehicles — the ABL and ABL II statutory consent forms record her certifying, in the standard formula, that “I consent to act as director of the company and certify that I am not disqualified from being appointed or holding office as a director of a company.” She also represented ABL as its proxy at Impress Ethanol’s shareholders’ meetings and was, corporate registry records show, a director of the group company KNM Global (S) Pte Ltd from June 2015.
Her father took direct board control of the ethanol company itself: the minutes of Impress Ethanol’s extraordinary general meeting of 21 September 2015 record that “Mr. Lee Swee Eng, Proxy of Asia Biofuels II Ltd., was elected as the Chairman of the meeting,” and that the shareholders “approved the appointment of new directors, Mr. Lee Swee Eng and Mr.
Ng Boon Su” in place of two outgoing directors — a move an independent director and a minority-fund shareholder protested in writing as improperly convened. In short, the people running the ethanol venture as it faltered were the Lees.
The plant became a money pit. KNM Group Berhad had guaranteed Impress Ethanol’s borrowings from the Export-Import Bank of Thailand — a guarantee covering THB1.21 billion and US$7 million, over an underlying THB900 million loan dating to 2009 and a THB300 million revolving facility. On top of that sat a THB2.78 billion bond (about RM347 million) guaranteed by the Credit Guarantee and Investment Facility, an Asian Development Bank trust fund.
The bond had been raised to finance the plant’s second-phase expansion — but that phase was never built. KNM was unable to meet the bond when it fell due: it defaulted on 18 November 2021, forcing CGIF to pay the bondholders on KNM’s behalf on 15 December 2021. KNM’s management blamed the pandemic and the plant’s operating conditions.
The default tipped the group into open distress — and left an obvious question hanging over the venture the family controlled: if the proceeds were raised to build an expansion that never materialised, where did the money go, and why was there nothing left to repay the bond?
The securities judgment
The most serious mark against Lee personally is a matter of regulatory record. On 29 April 2020 the Securities Commission Malaysia filed a civil action against him for insider trading — a breach of section 188(2) of the Capital Markets and Services Act 2007 — over the disposal of KNM Group shares while he was in possession of inside information. On 23 August 2022 the High Court entered a consent judgment. Lee was ordered to disgorge the loss he had avoided, pay a civil penalty and costs, and was barred for five years from being a director of any public-listed company and from dealing in securities. This was a civil action resolved by consent; no criminal conviction of Lee is on the public record.
Loss of control
As KNM faltered, Lee’s grip on his own company loosened. In September 2021 MAA Group, led by Tunku Datuk Yaacob Khyra, emerged as a substantial shareholder, acquiring a 7.01% block of 233 million shares on the open market for RM52.89 million (about 22.7 sen apiece) and, in a separate off-market direct business transaction, buying a stake directly from Lee. Boardroom changes followed: Lee’s wife Gan Siew Liat resigned as executive vice-chairman in mid-2021, and Lee stepped back.
MAA went on to become KNM’s largest shareholder, overtaking Lee, whose stake had fallen from its 2007 peak of about 26%. In July 2022 Lee transferred a block of shares to his daughter, Sara Lee Mei Ching, and he later disposed of further shares through direct business transactions until he ceased to be a substantial shareholder of the company that carried his initials.
PN17, delisting and collapse
On 31 October 2022 KNM was classified as a PN17 company — Bursa Malaysia’s category for financially distressed issuers — after its external auditor cast doubt on its ability to continue as a going concern. Creditors filed winding-up petitions, and group-level defaults ran past RM1.3 billion. The endgame centred on the crown jewel: KNM agreed to sell Borsig, the German unit, to Japan’s NGK Insulators for €270 million, and later sued NGK for RM600 million over what it called a botched sale. Bursa Malaysia rejected KNM’s plan to regularise its finances, citing the absence of sustainable earnings and a credible turnaround. The company withdrew its appeal, and KNM was delisted on 5 November 2025, ending 22 years as a public company.
The story is not over
Delisting was not the end of the reckoning — it was the start of a wind-down. There is no rescue to engineer: the operating business that made KNM’s name has effectively ceased to function, and what value remains sits mainly in the foreign units, which are being sold off as assets to be liquidated rather than revived — against liabilities the group’s assets are not enough to cover. Creditors are now in the process of taking control of what is left. The prolonged failure to produce any viable plan is itself telling: after years of drift, neither creditors nor shareholders appear to retain confidence in the existing board and management.
As that process unfolds, the conduct of the principals is likely to come under harder scrutiny — both Lee Swee Eng, the founder whose family ran the ventures that helped sink the group, and Tunku Yaacob Khyra, the financier who moved in as Lee moved out. What the public and documentary record already sets down is a debt-laden expansion, a family-controlled Thai ethanol venture that borrowed to build a second phase that never rose and then could not repay the debt, a civil insider-trading judgment, PN17 distress, winding-up petitions and a delisting. Big questions remain — chief among them what became of money borrowed against an expansion that was never constructed.
To date, no one has been able to trace it. How the liquidation apportions the losses, and what it turns up about the years before the fall, is the chapter still being written.