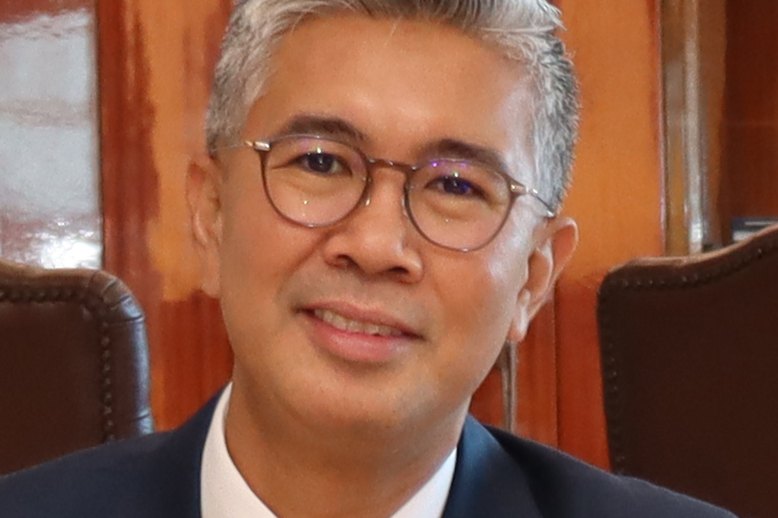
Finance Minister Tengku Datuk Seri Zafrul Abdul Aziz announced on 7 September in Petaling Jaya that the government intends to raise the legal debt ceiling from the current 60 % of gross domestic product (GDP) to 65 %. The move is aimed at preserving fiscal space for ongoing stimulus measures while avoiding disruption to the domestic bond market.
At present, Malaysia’s debt‑to‑GDP ratio stands at roughly 58 %, but Treasury forecasts indicate the figure could exceed the 60 % limit before the end of the year. The minister explained that the administration is still operating within the existing ceiling, yet any breach would be minimal unless Parliament authorises a higher threshold. The proposal is slated for cabinet consideration next week, after which it will be presented to the legislature.
The timing of the amendment is significant. The Malaysian economy continues to absorb the fallout from the COVID‑19 pandemic, and the finance ministry has pledged ongoing assistance for households and businesses.
Without additional borrowing capacity, those commitments could clash with the statutory cap, potentially forcing a halt to new stimulus. The World Bank has commented that expanding the debt limit would give the government greater leeway to implement fiscal policy, but it also warned that debt must remain sustainable. This balance between flexibility and fiscal discipline is expected to dominate debate when the bill reaches lawmakers.
When questioned about the possibility of tapping overseas markets to fill any financing gap, Tengku Zafrul dismissed the idea, stating that all stimulus packages will be funded through the local ringgit market. He cited sufficient domestic liquidity to absorb the required issuance and emphasized that relying on local investors shields Malaysia from exchange‑rate risk, even though it places the borrowing burden on domestic banks and institutional investors.
For the bond market, the practical implication is a likely increase in government paper. The key question for investors—pension funds, insurers and banks—is whether they will purchase the additional securities without demanding substantially higher yields. The minister expressed confidence that the system has enough slack to accommodate the extra issuance.
While the proposal creates additional headroom, it also acknowledges that the existing margin has already been eroded. A higher ceiling would allow the government to continue aid and stimulus programmes without an immediate legal impediment, effectively buying time for the recovery.
However, it also means future administrations will inherit a larger stock of debt, with each percentage point of GDP adding servicing costs that compete with spending on education, health and infrastructure. Opposition members are expected to seek assurances that any extra borrowing will be temporary and linked to specific recovery initiatives. The minister has not provided a timetable for returning to a lower debt ratio, leaving room for interpretation and concern among some legislators.
In summary, the government’s strategy rests on three assumptions: domestic liquidity will remain ample, bond yields will stay within manageable levels, and the economy will grow quickly enough to reduce the debt‑to‑GDP ratio over time. The upcoming cabinet decision will be the first test of this approach; a parliamentary vote will follow.
Should any of these assumptions prove inaccurate, the repercussions could affect the budget, bond market and broader economic outlook. The next few months will reveal whether the gamble of raising the debt ceiling to 65 % of GDP delivers the intended stability for Malaysia’s recovery.