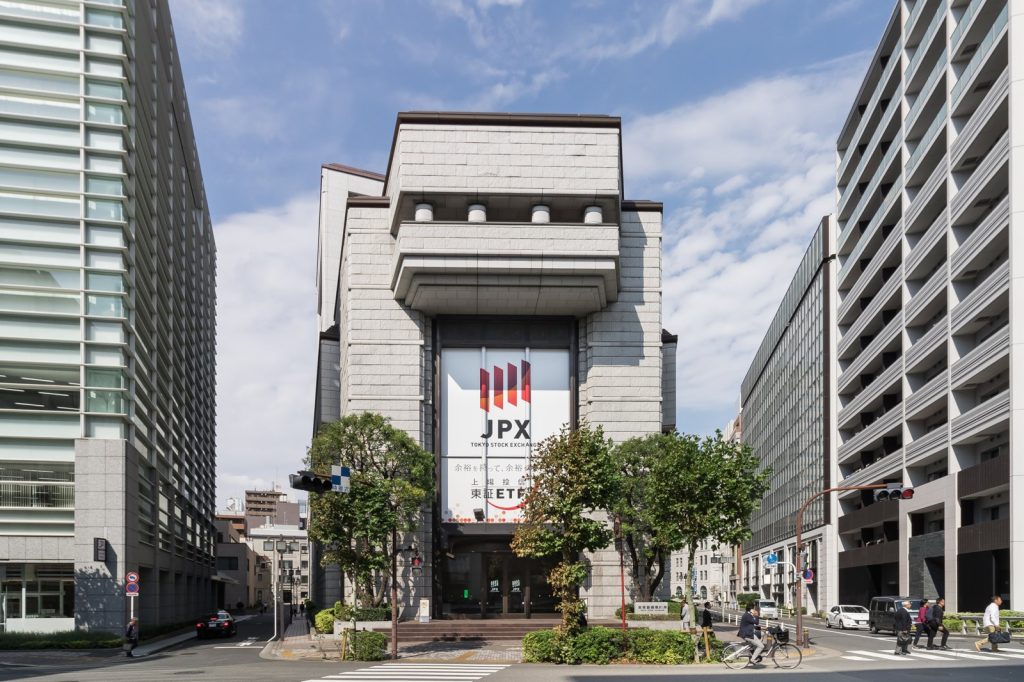
TOKYO, September 24 — Asian equities closed mixed on Thursday, with no single development driving the session. The bottom line for investors: this was a market moving on cross-asset signals rather than news. Traders weighed three forces — oil prices, US government bond yields, and currency fluctuations — and the result was a split regional close.
Some benchmarks advanced while others declined, a pattern that reflects the different investor bases and sector weights of Asia’s major exchanges.
Oil Feeds Straight Into Earnings
Crude was the first pillar. Most Asian economies are net energy importers, so benchmark prices feed directly into the cost base of airlines, shipping firms, manufacturers and utilities. Those costs then show up in national inflation and trade-balance figures.
Oil also moves the currencies of the region’s energy exporters and importers, which links the commodity to the foreign-exchange leg of the story. US Treasuries supplied the second signal.
The yield on US government debt is the benchmark for global borrowing costs, and when it moves, the relative attractiveness of Asian assets shifts with it. Higher US yields typically tighten global financial conditions; lower yields can support risk appetite. The direction of the dollar matters too, because it helps set the flow of capital into and out of emerging Asian markets.
Currencies Matter Most for Exporters
Currency moves were the third pillar, and for Asia’s export-oriented economies they bite hardest. A weaker local currency makes exports more competitive while raising the cost of imported goods and dollar-denominated debt. Regional monetary authorities have at times intervened or adjusted policy in response to sharp swings, and traders watch major pairs for signals about capital flows.
Asia’s equity trading is spread across a network of exchanges — the Tokyo Stock Exchange, the Hong Kong Stock Exchange, the Shanghai and Shenzhen exchanges in mainland China, the Korea Exchange in Seoul, and the Taiwan Stock Exchange, among others. Each keeps its own hours and its own investor base.
That is why a mixed regional session often means performance diverging between technology-heavy, export-dependent and domestically driven indexes. The interplay of oil, US bonds and currencies is a recurring theme because of where Asia sits in global trade. Many economies in the region depend on imported energy, export manufactured goods worldwide, and hold substantial foreign-exchange reserves.
That structure makes regional share prices unusually sensitive to commodity prices, US interest-rate expectations, and the direction of the US dollar.
The Travel Read-Through
The same variables carry direct consequences for travelers and the travel industry. Oil prices feed into jet fuel costs and therefore airfares. Currency movements change the cost of overseas trips and the value of travel spending.
Bond yields influence the broader economic conditions that shape consumer confidence and travel demand. A weaker yen, for example, makes Japan cheaper for foreign visitors but more expensive for Japanese traveling abroad, while a stronger dollar raises costs for Asian travelers heading to the United States.
No single figure or official statement dominated Thursday’s session. The mixed close illustrated how Asian markets continuously price in signals from energy, rates and foreign exchange — and how those signals transmit into the real economy and the travel sector. Investors will note that with no dominant catalyst on the calendar, the next moves are likely to come from the same three places: crude benchmarks, US yields, and the dollar.