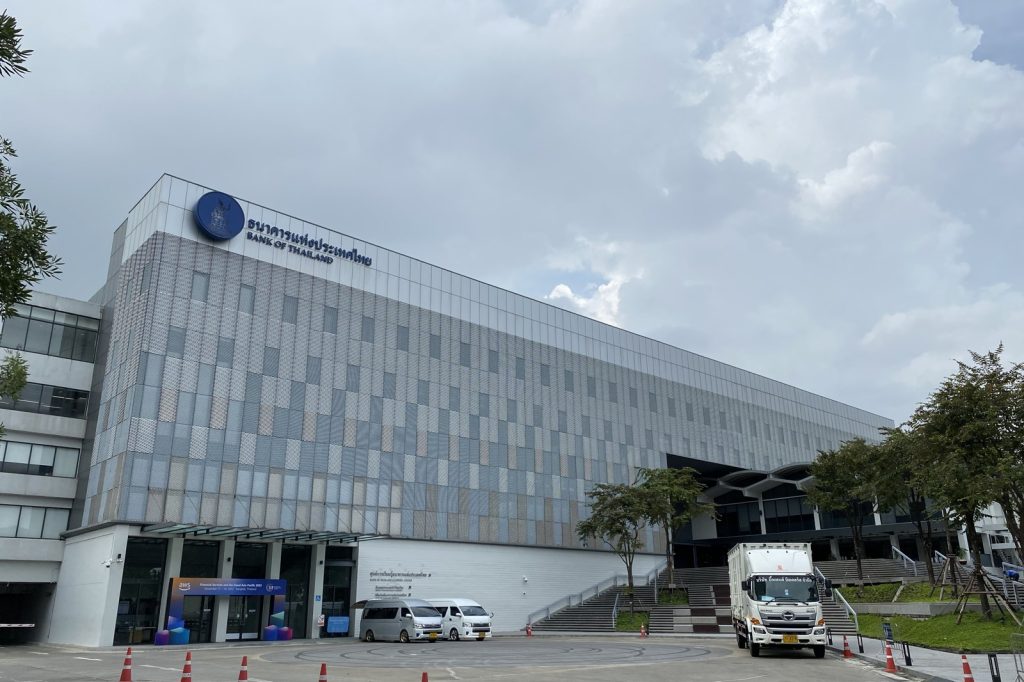
Bangkok, August 29 — Thailand’s economy shows signs of structural strain as the Bank of Thailand keeps its policy rate at 1% following the August 30 Monetary Policy Committee decision. This low rate reflects deeper vulnerabilities including household debt that exceeds 90% of GDP and a shrinking labor force. The nation’s aging population creates a demographic challenge that mirrors Japan’s prolonged stagnation.
Fewer workers enter the economy each year while tourism revenue remains constrained, amplifying deflationary pressures that limit growth options. Structural reforms remain limited, leaving monetary policy largely ineffective to stimulate demand.
The central bank’s decision underscores concerns over debt sustainability as Thailand confronts the rare condition of growing old before becoming wealthy. Weak consumer demand further complicates the outlook. With households carrying record debt burdens, spending power is limited and economic momentum stalls.
This dynamic creates a difficult cycle that few Asian economies have managed to reverse. What comes next matters most.
Thailand must address demographic shifts and debt pressures through targeted reforms. The path forward will test whether the country can break free from patterns that have held back growth for years. Thailand’s economic trajectory has increasingly drawn comparisons to Japan’s prolonged period of stagnation, particularly due to overlapping challenges of aging demographics, high household debt, and limited policy effectiveness.
The country’s population is aging rapidly, with a growing proportion of elderly citizens and declining birth rates, mirroring Japan’s demographic transition that began decades ago. This shift has reduced the size of the working-age population, constraining labor supply and long-term economic dynamism. As a result, Thailand faces a structural headwind that limits its ability to rely on traditional growth drivers such as labor-intensive exports and consumer spending.
Household debt in Thailand has risen to levels that exceed 90% of GDP, placing significant pressure on domestic consumption and financial stability. Much of this debt is held by families with stagnant or declining incomes, limiting their ability to spend or invest even when interest rates are low.
Unlike economies with more room for fiscal stimulus or younger, more adaptable populations, Thailand’s policy options are constrained by both fiscal discipline and demographic realities. The persistence of low inflation and weak demand has made it difficult for monetary policy alone to reignite growth, especially when debt overhangs suppress aggregate spending. These conditions have created a policy dilemma in which conventional tools appear insufficient.
The Bank of Thailand’s decision to maintain a 1% policy rate reflects concerns about financial stability and debt sustainability rather than confidence in future growth. With limited room to cut rates further and no immediate rebound in tourism or exports, the risk of prolonged stagnation grows.
Thailand’s experience underscores how demographic aging and high private debt can combine to produce a form of economic stagnation that is difficult to reverse without deeper structural reforms.
Sources
More Asia Travel & Food coverage: Thailand to Host International Healthcare Week 2026, Boosting Medical Hub Ambitions