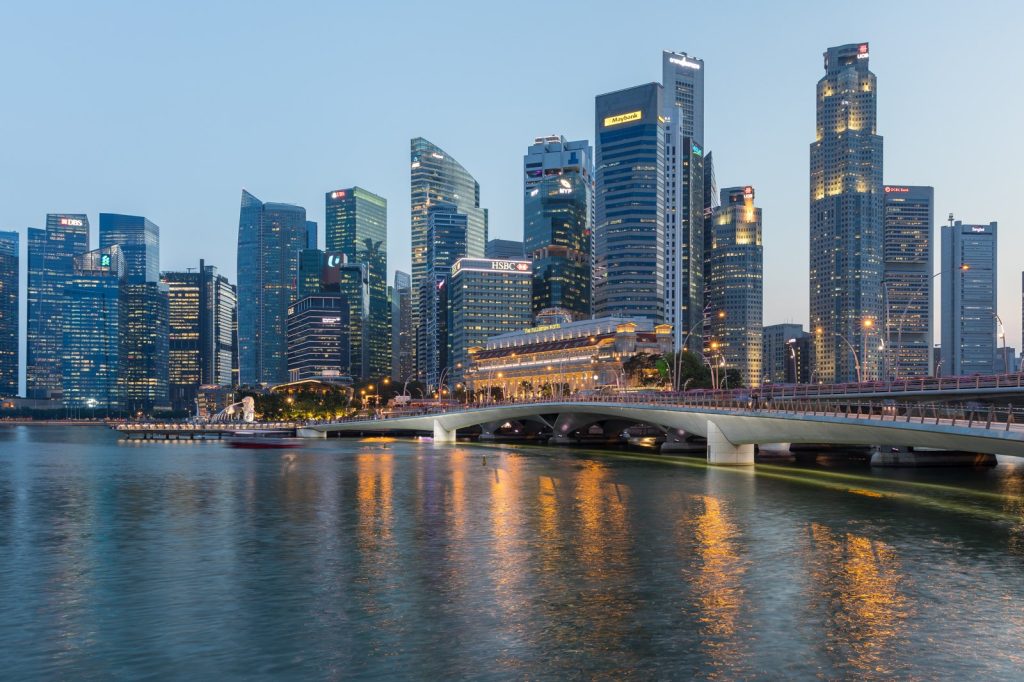
Singapore’s economy expanded by 1.3 percent during the first quarter of 2021, according to final figures released by the Ministry of Trade and Industry on May 22. This result marks an upward revision from earlier projections, indicating a swifter recovery than initially expected following a record contraction in the prior year. Government officials and analysts have characterized the acceleration as a promising sign, though the full-year forecast remains subject to potential adjustment later in 2021.
Authorities noted that improving conditions in key international markets, partly driven by vaccination campaigns in nations such as the United States, have contributed to stabilizing the external environment despite ongoing pandemic-related uncertainties.
Manufacturing and Trade Sectors Lead Recovery
The quarterly growth was largely propelled by expansions in specific industrial segments, including chemicals, electronics, and engineering, which demonstrated resilience amid persistent global supply chain disruptions. Wholesale trade activity saw a notable increase, rising 3.5 percent compared to a previously recorded rate of 1.8 percent. The retail sector grew at an annualized pace of 1.4 percent, while communication and information services experienced a significant acceleration from 2.6 percent to 6.4 percent per year. These figures suggest that core manufacturing and trade activities are rebounding more rapidly than service industries reliant on physical mobility.
Ministry officials attributed this diversified growth to the adaptability of local industries during extended periods of strict health measures.
Global Environment Shows Improvement but Risks Remain
Ministry of Trade and Industry representatives highlighted that the external economic landscape has shown signs of improvement, particularly among major trading partners, due to progress in domestic vaccination programs in countries like the United States that have facilitated cautious border reopenings. However, officials cautioned that downside risks persist because of the continuing pandemic worldwide.
The emergence of new virus variants and subsequent waves of infections in various nations threaten global supply chains. Singapore’s primary economic partners have tightened standard operating procedures in response to rising case numbers, potentially disrupting trade flows and affecting the country’s growth trajectory. The ministry emphasized that while the outlook is positive, vigilance is necessary to manage these external vulnerabilities.
Economists View Official Forecast as Conservative
Ms Selena Ling, OCBC Bank’s chief economist and head of treasury research and strategy, offered context regarding the government’s full-year projection. She noted that the 4 percent floor set by the Ministry of Trade and Industry was quite conservative given the depth of the previous year’s recession, which saw a record contraction of 5.4 percent. Economists and bankers in Singapore maintain that growth will likely remain between 4 to 6 percent for the remainder of the year, contingent upon the evolution of the COVID-19 situation globally.
The consensus among financial analysts is that while the current trajectory is encouraging, the pace of recovery depends heavily on how quickly global health conditions stabilize.
Potential Headwinds Ahead for 2021
Despite the optimistic first-quarter data, significant risks persist that could alter Singapore’s economic landscape for 2021. The primary concern remains the volatility of global health conditions and resulting policy responses from trading partners.
If major economies re-impose strict border controls or face prolonged lockdowns due to new virus variants, Singapore’s export-oriented economy could suffer setbacks similar to those experienced during earlier pandemic waves. The ministry acknowledged that while upsides exist in the form of recovering demand and stabilizing supply chains, downside risks are not negligible. Economic planners will closely monitor developments in key markets throughout the year.
The full-year forecast is expected to be revised in August, at which point a clearer picture of global and domestic economic situations will emerge. Until then, stakeholders are advised to prepare for potential fluctuations driven by external shocks.